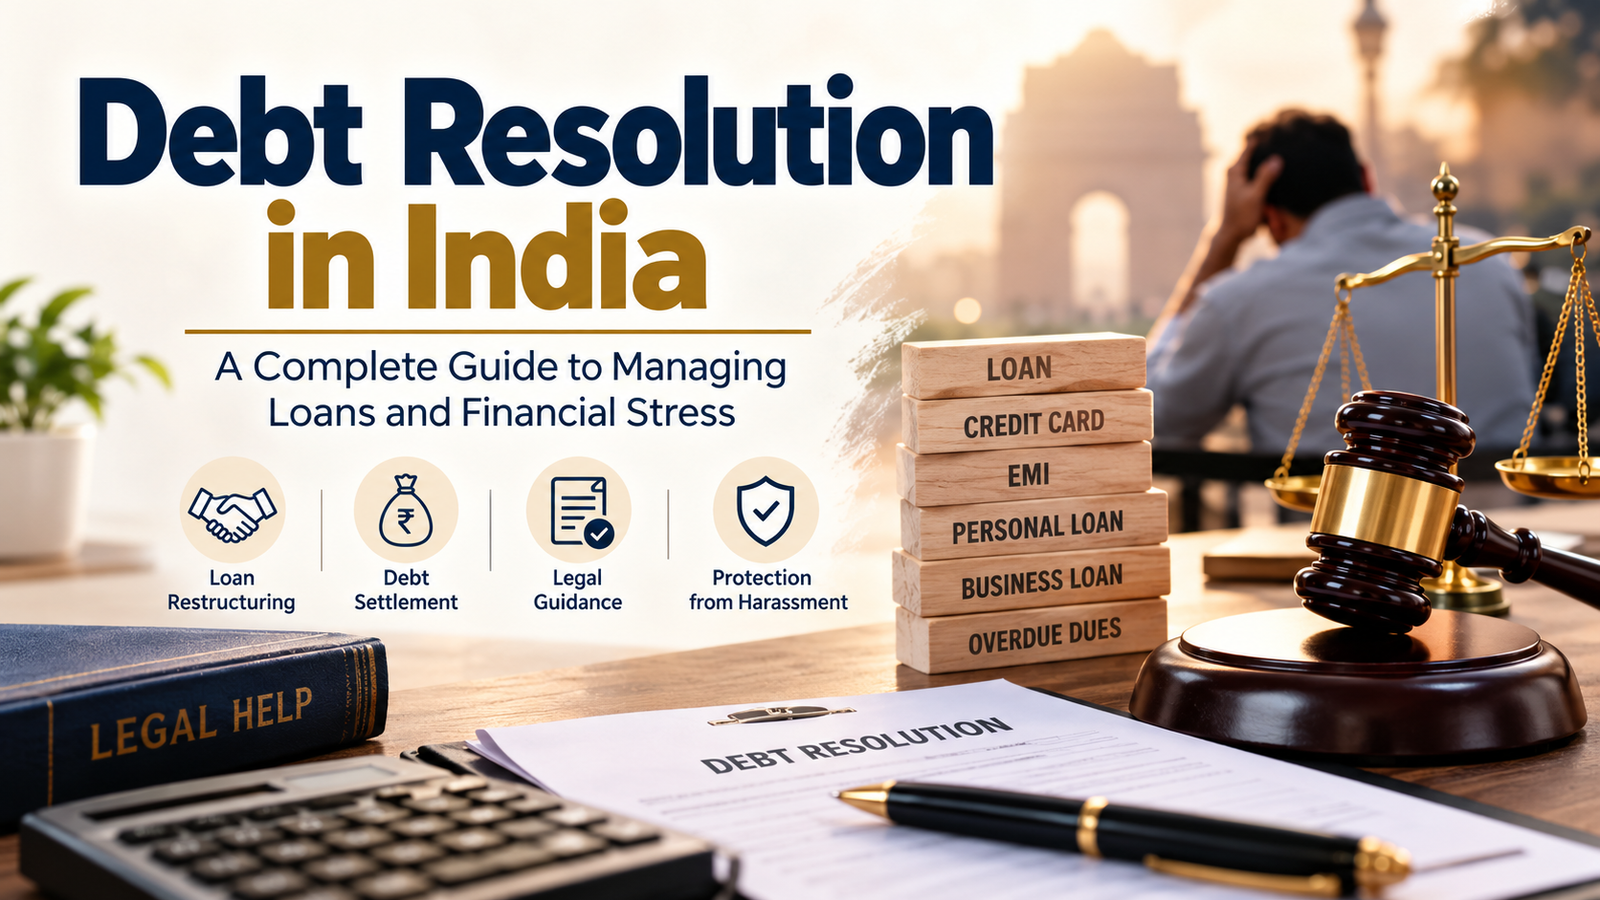
Debt Resolution in India: A Complete Guide to Managing Loans and Financial Stress
Financial difficulties can arise unexpectedly due to job loss, medical expenses, business losses, or changes in income. When loan payments and credit card bills become difficult to manage, the pressure can affect both financial stability and peace of mind. Understanding debt resolution in India can help borrowers explore practical, lawful options for handling outstanding dues.
Debt resolution involves assessing your financial situation and exploring possible solutions with lenders. Depending on your circumstances, these may include repayment planning, loan restructuring, negotiation, or settlement. At AdvoExpert, individuals can seek legal guidance for debt-related concerns and understand the options available for their particular situation.
What Is Debt Resolution in India?
Debt resolution in India refers to the process of addressing outstanding debts through suitable repayment arrangements, negotiations, restructuring, or other legally appropriate solutions.
The right approach depends on several factors, including your total outstanding balance, repayment history, income, loan agreement, and the lender’s policies. There is no single solution that works for every borrower, and debt settlement is not guaranteed.
Seeking professional guidance early can help you understand your obligations, evaluate available options, and make informed decisions.
Common Reasons People Face Debt Problems
People may experience repayment difficulties for various reasons, including:
- Income disruption: Job loss, reduced salary, or delayed payments can make monthly instalments difficult to manage.
- Business challenges: Reduced sales, cash-flow problems, or unexpected operating expenses can affect business loan repayments.
- Medical emergencies: Unexpected healthcare expenses can put pressure on household finances.
- Multiple credit obligations: Managing several loans and credit card balances simultaneously can make budgeting challenging.
- High borrowing costs: Interest charges and applicable fees can increase the total amount payable over time.
Identifying the main cause of financial difficulty is an important first step toward finding an appropriate solution.
Legal Options for Debt Resolution in India
Depending on the loan type and circumstances, borrowers may explore different approaches to managing outstanding dues.
1. Loan Restructuring
Loan restructuring involves requesting revised repayment terms from the lender. Depending on the lender’s policies and eligibility requirements, this may involve extending the repayment tenure or modifying instalment arrangements.
Restructuring is not automatic. Review the revised terms, total interest payable, fees, and long-term financial implications before accepting an offer.
2. Debt Settlement
Debt settlement involves negotiating with a lender to accept an agreed amount toward an outstanding debt, subject to the lender’s approval and a clear written agreement.
Before accepting a settlement, confirm the payment deadline, amount payable, treatment of the remaining balance, and how the arrangement may be reported to credit bureaus. A settled account can affect your credit history differently from an account fully repaid according to its terms.
3. Repayment Planning
A structured repayment plan can help borrowers prioritise essential expenses and understand how much they can reasonably allocate toward their debts.
Prepare a list of outstanding balances, interest rates, minimum payments, and due dates. Contact lenders promptly if you anticipate missing a payment rather than ignoring reminders or notices.
4. Legal Guidance for Loan Defaults
If you have received a legal notice, face a dispute with a lender, or are uncertain about your rights and obligations, consult a qualified legal professional. They can review the relevant documents and explain possible responses based on the facts of your case.
Professional legal assistance does not automatically cancel a debt or prevent a lender from taking lawful recovery action.
What Are Your Rights Regarding Recovery Agents?
Borrowers should be treated respectfully, even when repayments are overdue. Recovery activities must follow applicable laws, regulatory requirements, and the relevant lender’s obligations.
If you experience threatening calls, intimidation, abusive language, or other potentially unlawful conduct, keep a record of the incidents and preserve relevant messages or communications.
You can raise a complaint with the lender through its official grievance mechanism. Depending on the circumstances, further complaint or legal remedies may be available.
Do not assume that every recovery call is illegal. The nature, timing, conduct, and applicable rules matter when assessing a particular incident.
How AdvoExpert Can Help
AdvoExpert provides legal assistance for debt-related matters, including loan defaults, credit card dues, recovery agent harassment, business loan concerns, secured loans, and cheque bounce cases.
Its support process begins with understanding the situation and reviewing relevant documents. Based on the case, the team can help identify possible legal and financial approaches, explain relevant procedures, and assist with appropriate representation or negotiations where available.
For individuals exploring debt resolution in India, professional guidance can make it easier to understand the available options and the potential consequences of each approach.
The outcome of any case depends on its specific facts, applicable law, and the response of the relevant lender or authority.
Documents to Prepare Before Seeking Help
Having the relevant paperwork ready can make an initial consultation more productive. Consider gathering:
- Loan agreements and account statements.
- Credit card statements and payment records.
- Details of overdue instalments and outstanding balances.
- Communications received from the lender or recovery agency.
- Copies of legal notices or complaint records, if applicable.
- Documents showing your current repayment capacity, where relevant.
Share sensitive financial documents only through appropriate, secure channels.
Mistakes to Avoid When Managing Debt
When dealing with financial pressure, avoid making rushed decisions. These common mistakes can complicate the situation:
- Ignoring legal notices or important lender communications.
- Accepting verbal settlement promises without written confirmation.
- Taking additional expensive loans without assessing affordability.
- Paying unverified individuals who claim they can erase your debt.
- Assuming that a settlement will immediately improve your credit score.
- Signing documents without understanding their terms and consequences.
Always verify the identity of the person contacting you and confirm payment instructions directly with the lender through official channels.
Frequently Asked Questions
Can debt be settled in India?
Debt settlement may be possible if the lender agrees to the proposed arrangement. Approval, settlement amounts, and conditions vary by case. Obtain the terms in writing before making payment.
Can I get legal help if I cannot pay my EMIs?
Yes. A qualified legal professional can review your circumstances, explain your obligations, and discuss appropriate options, which may include contacting the lender about restructuring or other arrangements.
Does debt settlement affect my CIBIL score?
It can. A settled account may be reported differently from an account fully repaid, and this can affect your credit profile. Ask the lender how the account will be reported and review the written settlement terms.
What should I do if a recovery agent threatens me?
Keep records of relevant communications, contact the lender through its official complaint channel, and seek legal advice if the conduct appears unlawful or threatening.
How do I choose the right debt resolution approach?
Consider your repayment capacity, outstanding balance, loan terms, legal notices, and the potential financial and credit consequences of each option. Professional advice can help you compare suitable alternatives.
Get Professional Guidance for Debt Resolution in India
Financial difficulties can feel overwhelming, but understanding your rights and responsibilities is an important step toward making informed decisions. Review your outstanding obligations, communicate with your lender through official channels, and seek qualified assistance when you need help understanding your legal options.
AdvoExpert offers legal support for debt-related concerns, loan defaults, and recovery agent harassment. Contact the team to discuss your circumstances and explore an approach suited to your case.
Disclaimer: This article is for general informational purposes and does not constitute legal or financial advice. Outcomes depend on individual circumstances, applicable law, and lender policies.